The checkout is where enterprise revenue quietly leaks
Most enterprise storefronts treat the checkout as finished work. The design system is settled, the payment page passed review, the processor has been live for years. Then traffic arrives, a slice of it dies on the final screen, and nobody can explain why.
Visa has estimated that payment problems drive as much as 44 percent of digital shopping abandonment. That figure almost never shows up in a conversion report. A conversion report measures sessions against orders, and an order that fails at authorization just looks like a session that did not convert. The money disappears into the gap between the two.
The metric that describes that gap is the authorization rate: the share of submitted payment attempts an issuer approves. It is the rare number on an e-commerce site that is at once a technical metric, a fraud-tooling metric and a revenue metric, which is a good part of why it usually has no owner.
Why the authorization rate goes unmanaged
There are reasonable benchmarks to work against. Domestic recurring cards should authorize at 90 to 95 percent. Cross-border recurring volume at 85 to 90 percent counts as a well-optimized setup. Anything below 85 percent domestic or 75 percent cross-border warrants a diagnostic review, and plenty of established stores sit under those floors for years without anyone noticing.
The reason is structural rather than careless. Payment acceptance gets configured once, at launch, by whoever integrated the first gateway. Every decline that follows lands in a log file as a code. A technical decline caused by a malformed request looks exactly as alarming as a risk decline, which looks exactly like a customer with an expired card. No one separates the three, so no one sees that a meaningful fraction of the declines were never real.
Marketing owns traffic. Merchandising owns assortment. Finance reconciles settlements months later. Between them sits a payment path that decides whether the work all three of those teams did turns into revenue, and it is measured by default, if at all.
False declines cost far more than fraud
The scale is larger than most leadership teams assume. Datos Insights puts the global false decline rate at 1.51 percent of e-commerce sales, and projects global merchant losses from false declines above 231 billion US dollars in 2026, approaching 265 billion in 2027.
Set that against fraud losses and the picture changes. Aite-Novarica estimated global false decline losses above 443 billion dollars, against roughly 48 billion dollars in genuine e-commerce card fraud, a ratio of about nine to one. Riskified's reading of the same data puts the average merchant's exposure at up to 5.5 percent of annual revenue. A Statista survey found that 56 percent of US shoppers had a payment declined while buying online, the highest rate among the countries surveyed.
Every one of those declines is a customer who wanted to pay. The cost is not only the abandoned basket. It is the retry that succeeds on a competitor's site, the subscription that churns involuntarily, and the support ticket that costs more to resolve than the original order was worth.
Four levers that move approval rates
Solidgate's framework breaks authorization rate optimization into four layers: network tokenization, multi-acquirer routing, decline-aware retry logic, and 3-D Secure exemption strategy. Most merchants are pulling one or two of them. The gains compound when all four run together.
Network tokenization
This is the closest thing to free money in payments, and the numbers come straight from the card networks. Visa reports a 4.6 percent lift in authorization rates for card-not-present transactions that use network tokens instead of raw card numbers. Mastercard reports 2.1 percent. Adyen measures roughly 3 percent average uplift across merchants on its platform, and both Adyen's case data and Pagos's aggregated merchant data put the range at 2 to 7 percent depending on issuer mix, card file age and whether volume is digital-only.
The mechanism is straightforward. When a payment reaches an issuer as a network token, the scheme has already validated the credential and attached assurance data, so the issuer is looking at a stronger signal than a raw account number. Visa also associates tokenized traffic with a 30 percent reduction in online fraud and offers 5 to 10 basis points of interchange savings on it.
The operational benefit often matters more than the authorization lift. Tokens survive card expiry and reissue, because the network updates them in place. For any store with subscriptions or stored cards, that removes a whole category of involuntary churn that shows up in reports as a failed renewal rather than a lost customer.
Token provisioning is not uniform, which is where the remaining upside sits. A network token only helps on transactions that actually use one. In Latin America the overall provisioning rate sits near 57.5 percent, around 61 percent for Visa and 54 percent for Mastercard, which means a large share of eligible card-on-file transactions still go out as raw numbers.
Smart routing and provider redundancy
A single-gateway architecture inherits every weakness of that gateway, including its outages, at 100 percent. When a processor has a bad hour, the store stops taking orders and there is nowhere to send the traffic.
An orchestration layer routes each transaction by currency, card type, issuer region and live performance, and re-routes when a provider degrades. Juspay reports that merchants typically see a 2 to 4 percent authorization increase immediately, 5 to 10 percent with continued optimization, and 10 to 15 percent overall through smart routing. Yuno reports an average 8 percent uplift from smart routing alone. Reserva, a Brazilian fashion retailer, added four percentage points of approval in under three months by consolidating routing and fraud decisions through one layer. Arcos Dorados, which operates McDonald's across Latin America, unified payment operations in 21 countries on a single orchestration layer instead of rebuilding market by market.
Routing also reduces cost. Providers negotiate differently by region and volume, so directing traffic intelligently trims processing fees rather than just lifting approvals.
Retry logic and decline classification
Not every decline is a no. Soft declines, which cover insufficient funds, temporary issuer holds and timeouts, make up 80 to 90 percent of failures in most verticals and are recoverable at 40 to 70 percent. Hard declines, such as closed accounts, invalid numbers and blocklisted credentials, should never be retried because the second attempt fails too and the noise obscures the real problem.
The classification step is where most setups underperform. Systems that read the decline code before deciding to retry recover 70 to 85 percent of recoverable failures. Fixed calendar schedules that apply the same logic regardless of decline code land between 40 and 60 percent. Paddle's data shows that adding three extra retries inside the standard dunning window lifted failed payment recoveries by 20.2 percent, and moving the first retry from 2 hours to 24 hours improved recovery by a further 6.5 percent.
There is a ceiling. Card networks monitor retry behavior and penalize excessive attempts, so retry strategy is a scheduling problem rather than a volume problem. Time the attempt to the likely cause: an insufficient-funds decline has a better chance after a payday than twenty minutes later. Combined with multi-provider orchestration, decline-aware retries recover 15 to 25 percent of initially declined transactions.
3-D Secure without punishing good customers
Strong customer authentication cuts fraud, and it manufactures its own false declines when shoppers fail or abandon the challenge. A challenge that pushes away one in ten legitimate buyers costs more than the fraud it prevents.
The fix is exemption strategy rather than switching authentication off. Transactions that carry strong signals, such as an established customer on a recognised device with a healthy order history, are candidates for a risk-based exemption. Repeat buyers should rarely see a challenge. When a challenge is genuinely needed, keeping it inside the payment page rather than bouncing the shopper to an issuer page and back reduces abandonment on its own.
What an orchestration layer actually is
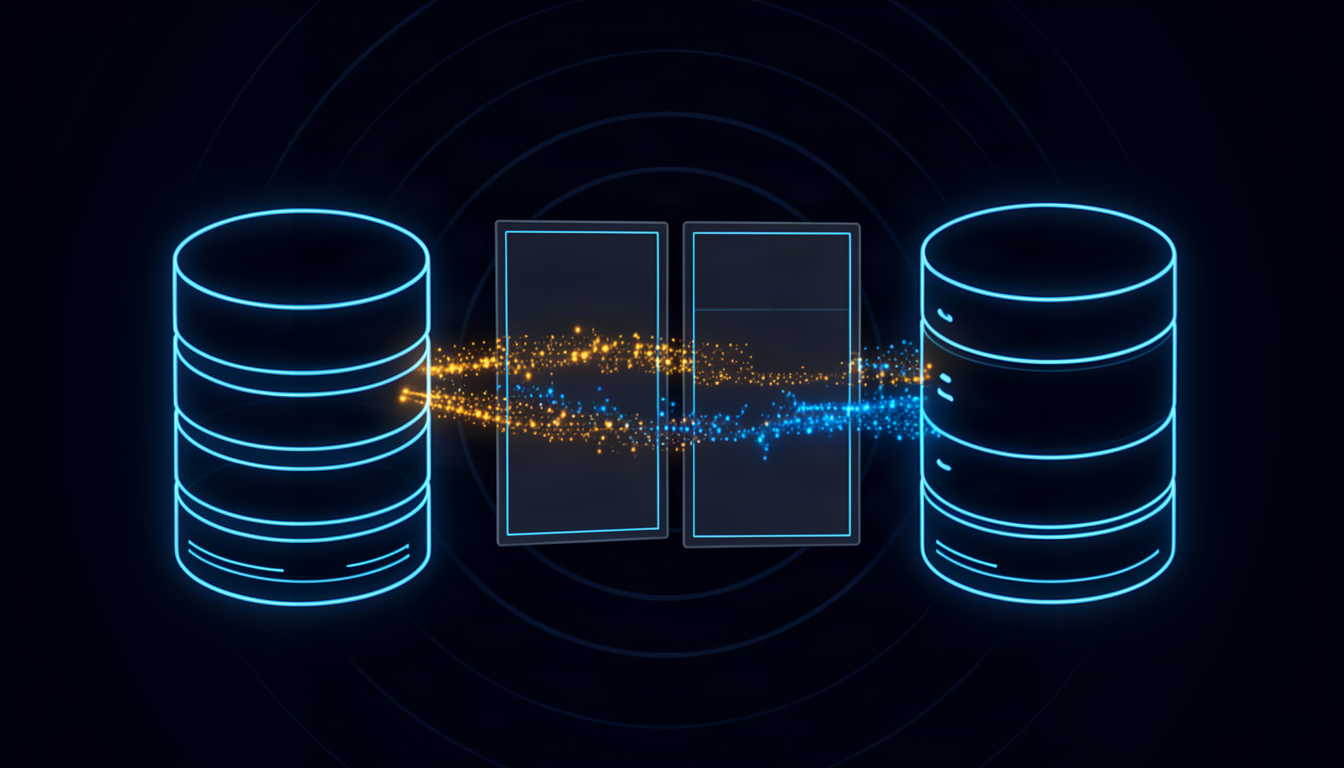
Payment orchestration is a single integration point that sits between the checkout and multiple acquirers and payment service providers. It owns routing rules, the token vault, the retry engine, unified reporting and reconciliation, and a consolidated PCI scope, so the storefront talks to one API while several providers compete for the transaction.
One architectural decision deserves attention before any vendor conversation. Token ownership and portability determine how expensive it will be to change providers later. If customer payment credentials are trapped inside a single provider's vault, adding a second acquirer or renegotiating rates years from now means either abandoning stored cards or a migration project. Portability is worth negotiating before it is needed, not after.
Local payment methods and local acquiring
Cards are not the whole picture in every market, and the gap between a card-only checkout and a locally tuned one is measurable.
Canada is a useful example. Interac Debit became available for online and in-app payments through Stripe in February 2026, having previously been limited to in-person transactions. Digital wallets are forecast to reach 43 percent of Canadian e-commerce volume by 2027, against 28 percent at the point of sale, with Apple Pay used by 42 percent of wallet owners, PayPal by 23 percent and Google Pay by 22 percent. Credit cards still account for close to half of Canadian payment volume and are expected to shed up to 10 percentage points by 2027. For cross-border sellers, Nuvei's guidance is blunt: acquiring locally in the customer's market, alongside orchestration and smart routing, is the fastest route to higher approval rates.
Instrumentation before optimization
None of this can be tuned without measurement, and the measurement is not a single dashboard number. A useful payment instrumentation set includes:
- Authorization rate segmented by issuer and BIN, region, payment method, device and new versus stored credential
- A decline taxonomy that separates technical, risk and compliance causes instead of lumping them into one failure count
- An estimate of false declines, built from successful retry purchases and the volume of payment-related support contacts
- Webhook delivery reliability and idempotency on order state, so a duplicate event cannot double-charge or double-fulfil
- Time to recover, measured from the first decline to the successful payment attempt
With those in place, routing and retry rules can be A/B tested on live traffic rather than argued about. A change to 3-D Secure exemption logic is then a measurable experiment with a revenue outcome attached, which is what gets it approved and kept.
Fixing revenue the store already earned
Traffic acquisition is expensive and competitive. Retaining a customer who has already entered card details and pressed pay is neither. The gap between a 91 percent authorization rate and an 87 percent one is not a rounding error on a store doing meaningful volume, and it is recoverable work rather than a growth strategy.
The sequence that tends to work: instrument the payment path, tokenize the card file, classify declines properly, add a second provider, then tune authentication. Each step has a measurable effect, and each one compounds the last. None of it requires rebuilding the checkout.
If the authorization rate is unknown, or known and below the benchmarks above, Tech Hub Services can instrument the payment path, build the decline taxonomy, and implement the routing and retry logic that recovers transactions the store has already earned.